
Srinagar, Apr 15: The sharp decline of Jammu & Kashmir’s poultry sector – once a model of self-reliance- has brought into focus serious concerns over ease of doing business, with stakeholders pointing to policy disruptions, lack of institutional support and delayed regulatory response as key factors behind the reversal.
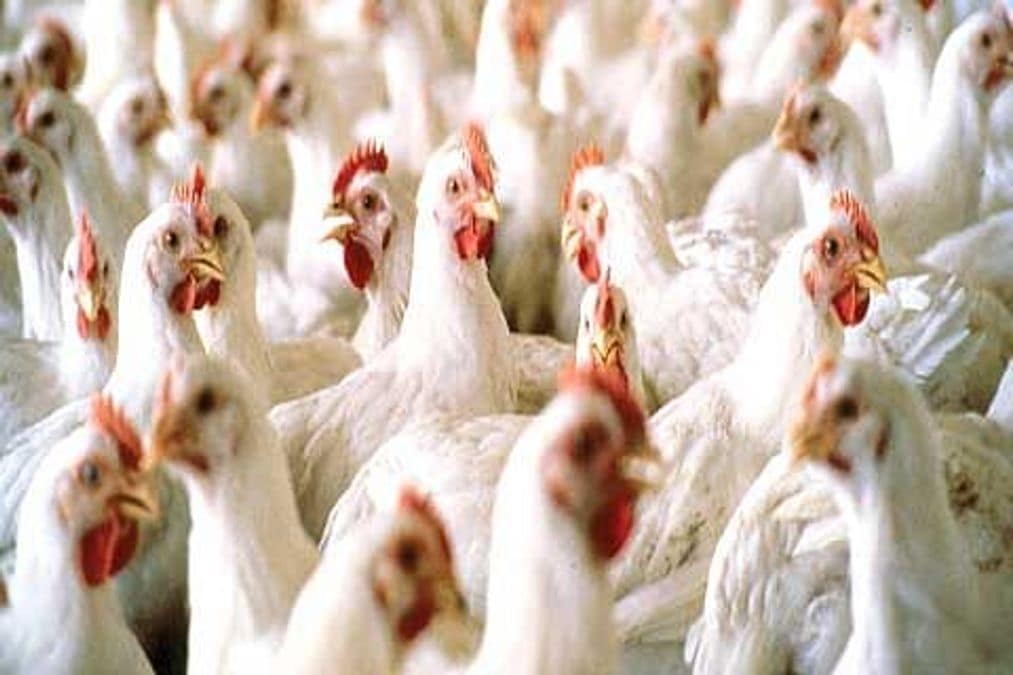
Until 2014, the sector had achieved nearly 85 per cent self-sufficiency in meeting local demand.
This growth was driven by a calibrated policy framework that included the imposition of a toll tax on imported poultry to ensure a level playing field for local producers, along with tax relief on one-day-old chicks. These measures enabled the sector to expand rapidly, creating a robust ecosystem comprising thousands of units and generating large-scale direct and indirect employment across farming, feed supply, transport, veterinary services and local trade networks.
However, the post-2014 period marked a turning point, not due to market forces but as a result of policy changes that dismantled the enabling framework without adequate safeguards. The introduction of the Goods and Services Tax (GST) in 2017, coupled with the abolition of toll and entry taxes, exposed local producers to an influx of cheaper poultry imports from outside markets. This, stakeholders argue, created an uneven competitive environment.
Producers in Jammu & Kashmir operate under inherent structural constraints, including higher input costs, dependence on externally sourced day-old chicks and feed, harsh climatic conditions that increase mortality rates, and the absence of integrated infrastructure such as hatcheries and feed mills. Competing with large, vertically integrated producers from other regions under such conditions proved unviable.
The consequences were immediate and far-reaching. Local production steadily declined, and a sector that once met the bulk of regional demand now caters to only 15–20 per cent of consumption. This shift has pushed the region back into import dependence, resulting in price volatility, supply vulnerabilities and loss of local value addition.
The situation worsened further after 2019, when the inflow of dressed and frozen poultry – often from unverified and poorly regulated sources -entered the market unchecked. Over time, this not only eroded the market share of local producers but also raised serious concerns regarding food safety, cold chain integrity and public health. Administrative intervention came only after reports highlighting unhygienic and questionable meat sources surfaced, underscoring a delayed regulatory response.
Analysts note that the decline reflects a lack of institutional foresight. At no stage was there a visible effort to assess the likely impact of policy shifts on an existing, functioning and nearly self-sufficient sector. The transition was abrupt, uncalibrated and disconnected from ground realities, leading to systemic disruption.
Equally concerning has been the lack of financial and institutional support during the period of stress. Poultry farmers have faced inconsistent and often discouraging responses from the banking system, with no structured accountability despite the sector’s importance for agriculture and rural livelihoods. Access to affordable credit, working capital and risk mitigation through insurance has remained uncertain, leaving many units to absorb sustained losses and pushing several towards stagnation or closure.
Infrastructure deficiencies have further compounded the crisis. The absence of functional hatcheries, feed mills and parent stock facilities has kept the sector heavily dependent on external suppliers, exposing it to high input costs and frequent supply disruptions. These foundational requirements for long-term viability have remained largely unaddressed.
The decline appears particularly paradoxical in light of the Holistic Agriculture Development Programme (HADP), which identifies poultry as a priority segment for transforming farmers into agripreneurs and building enterprise-led value chains. Poultry, with its short production cycles, high labour absorption and strong market demand, aligns closely with this vision and had already demonstrated its potential in the past. However, instead of consolidating these gains, the existing ecosystem was allowed to weaken.
The contradiction between policy intent and ground reality is stark. While HADP speaks of strengthening feed infrastructure, hatcheries, credit linkages and market systems, the absence of timely support for existing units has limited its impact on the ground.
The fallout has been both economic and social. Thousands of livelihoods have been disrupted, entrepreneurial incomes have weakened, and a significant opportunity for employment generation and trade balance improvement has been compromised. A sector that had the potential to move towards surplus production, processing and even exports has instead slipped into decline.
Stakeholders point out that warning signs had been visible for years and concerns repeatedly raised, yet the policy response remained delayed, fragmented and largely reactive.
The trajectory of the poultry sector now stands as a cautionary example of how unexamined policy changes and official apathy can undo years of progress. In a region striving for economic resilience, employment generation and self-sufficiency, the decline underscores the critical need for responsive policies, coordinated and grounded in local realities to truly improve ease of doing business.
About The Author